Casualty Losses: What You Need to Know to Help Your Business Recover from a Natural Disaster
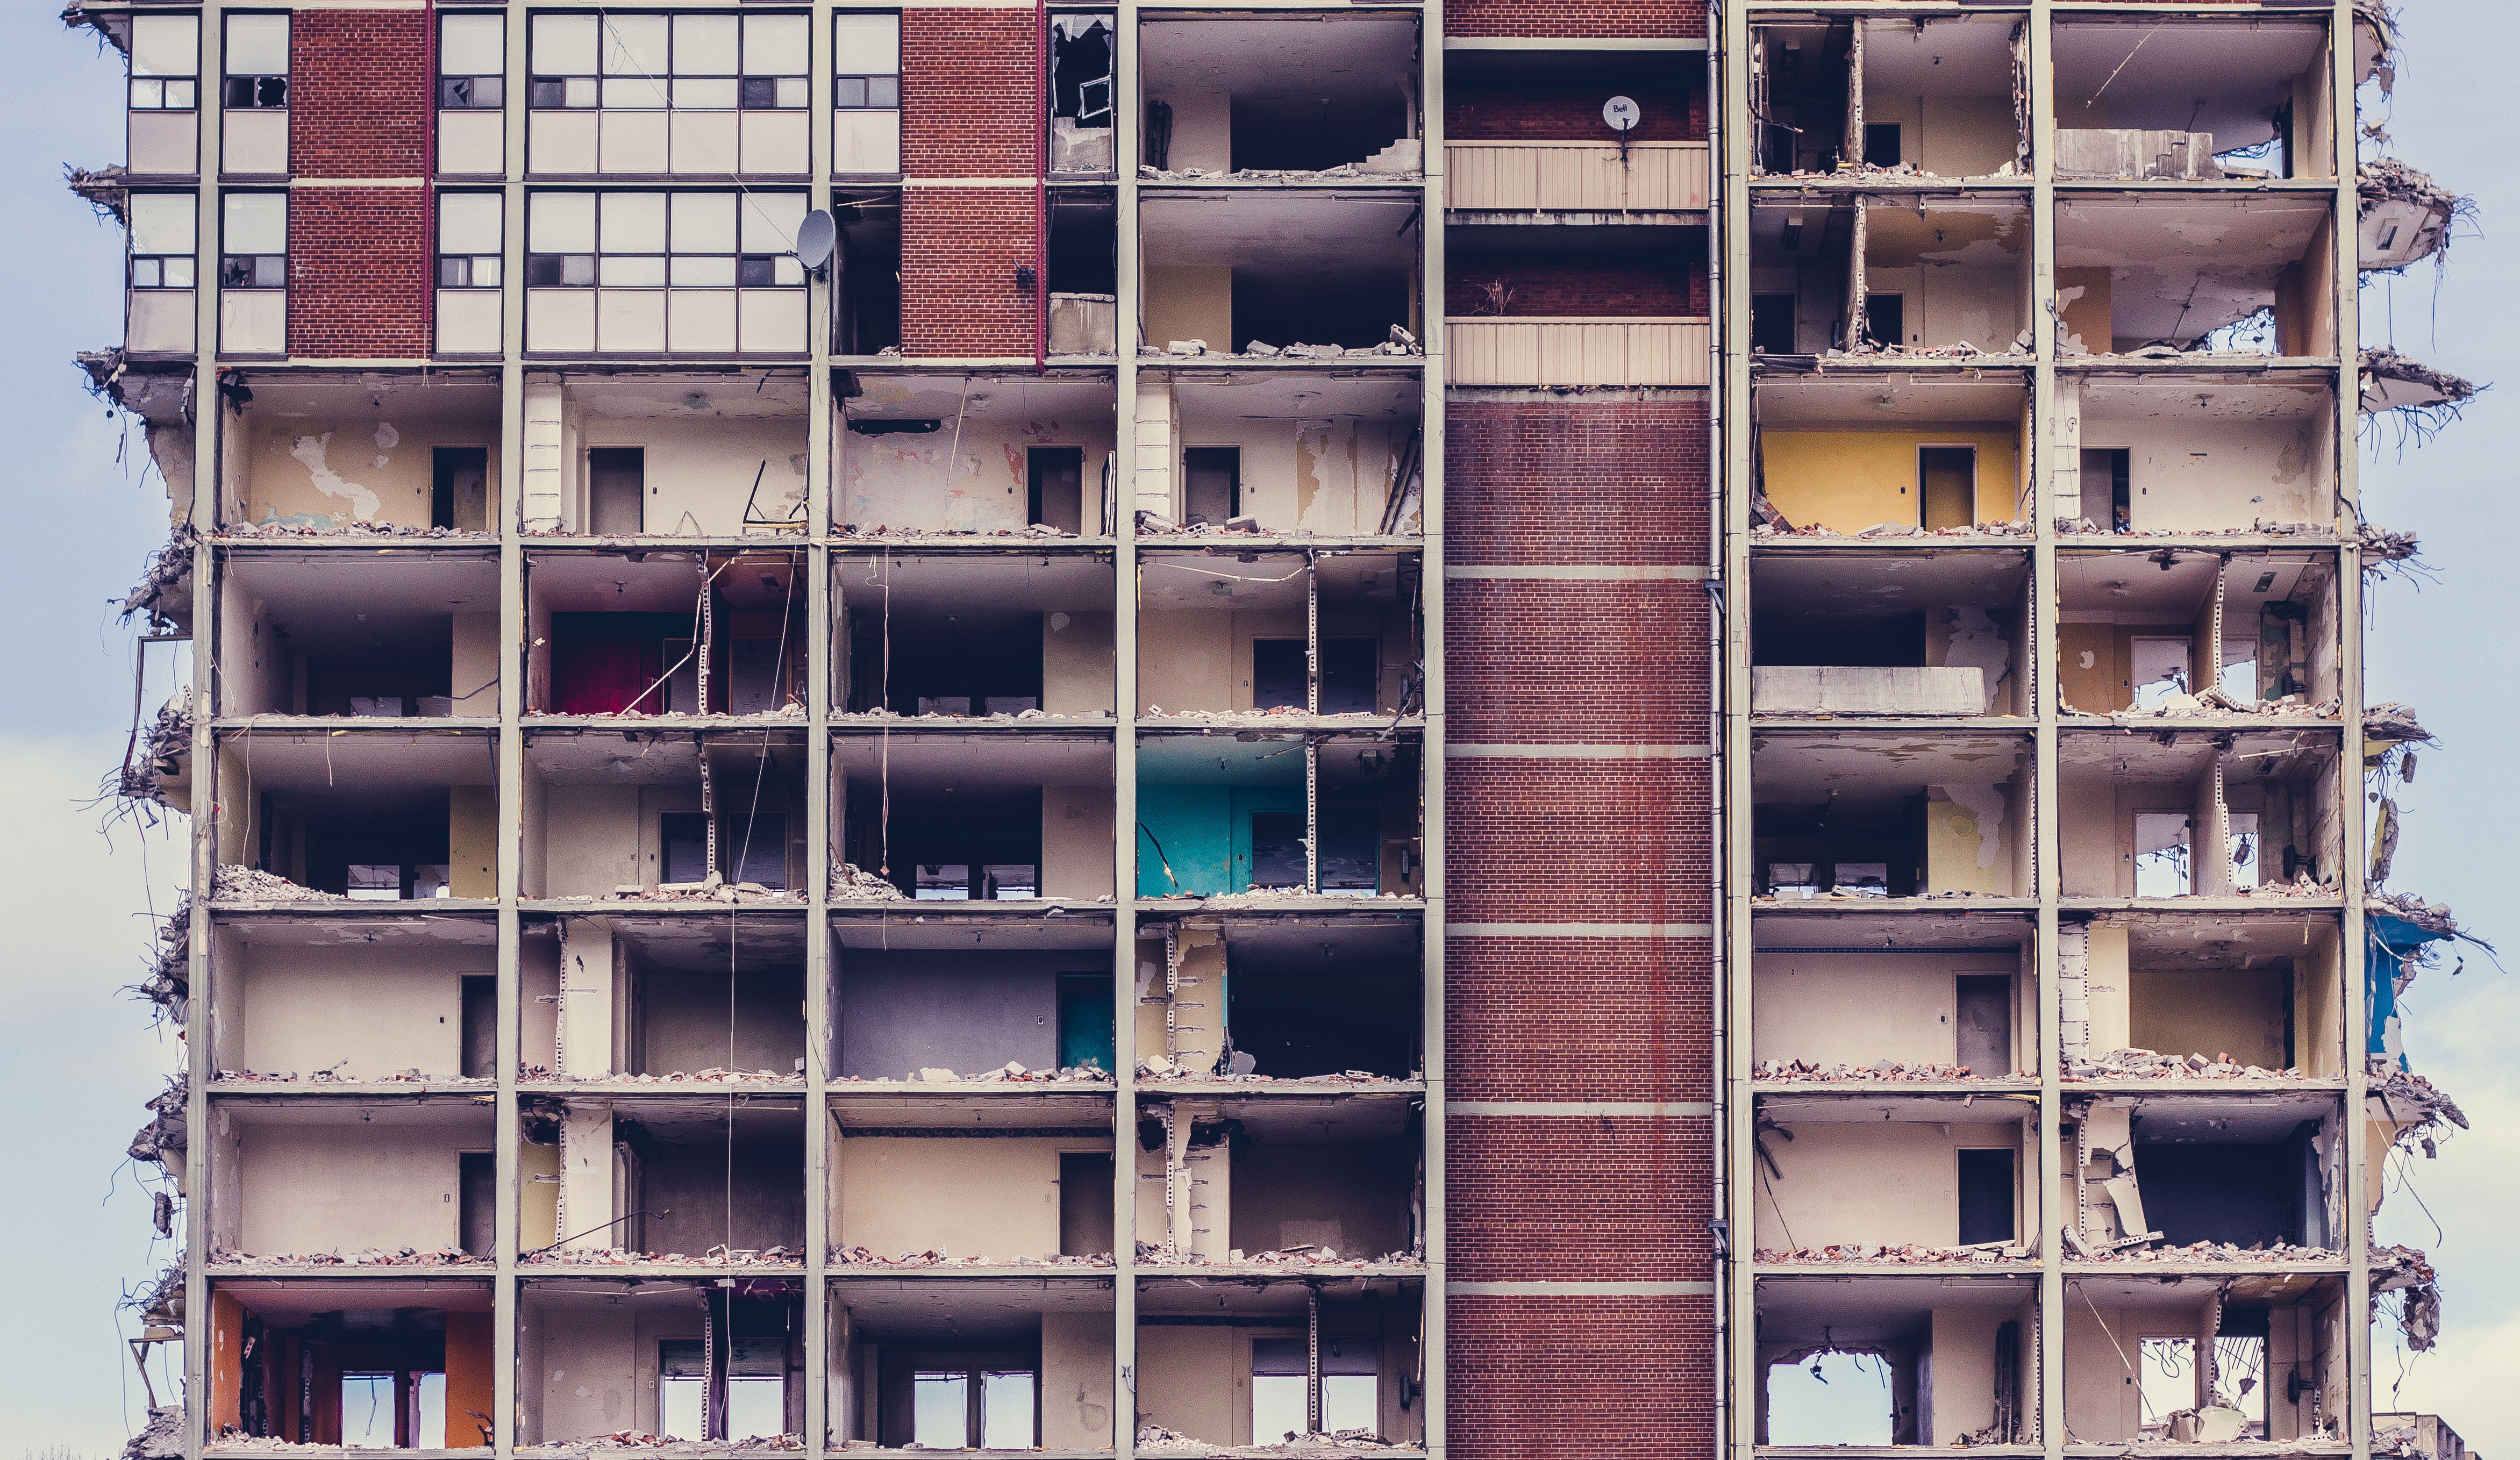
Natural disasters and the resulting recovery can be burdensome and even devastating for some businesses.
After a disaster, it can be hard to know how to get your business, its operations and its finances back on track, but there are many options available to help impacted companies.
Depending on a business’s specific situation, casualty losses may be able to help companies start on the road to recovery.
What Is a Casualty Loss?
A casualty loss is defined as the damage, destruction or loss of property resulting from an identifiable event that is sudden, unexpected or unusual, such as a fire, flood, hurricane, tornado or other natural disaster.
A casualty loss is calculated as the lesser of:
- The fair market value of the property immediately before the casualty less the fair market value after the casualty, or
- The adjusted basis of the property
This loss is then reduced by any insurance, salvage value and related reimbursement received or reasonably expected to be received. Please note that in the event that the business property is totally destroyed, then the loss is the adjusted basis.
Who Can Take a Casualty Loss and When Is It Recognized?
The Tax Code allows for the deduction of a loss if it is connected to a trade, business or a transaction entered into for profit. A casualty loss is generally recognized in the year it is sustained. However, if there are issues with determining the amount of insurance that may be received, then the loss is not recognized until the reimbursement outcome is reasonably certain.
What Should I Prepare or Know Now?
Here are a few tips that may help if you’re looking to make a casualty loss claim:
Keep Good Records
Be sure to track all expenses related to cleanup versus repairs and provide clear descriptions of the transactions. These should be tracked separately from your routine business repairs and maintenance. Review your current depreciation schedules and identify all assets impacted by the casualty event.
Know Your Insurance Coverage
Be aware of deductibles. Does your policy provide replacement cost coverage or actual cash value? Does your policy reimburse expenses if your business must relocate? Does your policy include business interruption insurance?
Be aware that business interruption insurance proceeds that replace lost business profits are generally taxable as gross income and would not be included in proceeds for replacing damaged property.
Know the Disaster Area Specifications
Know that if you have a business in a qualifying federal or state disaster area, you may have additional relief regarding tax deadlines and tax payments. Available relief is time sensitive and limited to impacted areas. Please consult the IRS website for issued guidance.
Understand Casualty Gains
Know that you may have a casualty gain if insurance reimbursements are more than the adjusted basis of the property.
You can elect to defer the gain recognition on your tax return by purchasing similar replacement property within a period that begins when the casualty occurred and ends two years after the close of the first tax year in which any part of the gain is realized.
Generally, when replacing property, the replacement property must have a similar use to the property that was destroyed. There are some different rules if the property destroyed was in a federally declared disaster area.
It’s important to note that if you do not replace the property during the two-year period, gain is recognized. These rules can be complex, so it’s important to talk through them with an advisor if you find yourself in this position.
Connect With Your Tax Advisor
Talk to your tax advisor as soon as you can about what information is needed to calculate the casualty gain or loss and help plan for any elections that might need to be made.
How Can I Learn More About Casualty Losses for My Business?
We know that not every situation is covered in the information above, and each property owner’s specific circumstance will be different.
The IRS has answered common questions from disaster victims specifically about casualty losses. You can access the IRS website here to learn more about how to determine and compute casualty losses.
The most effective way to obtain reliable insight and advice for your business during hurricane or disaster recovery is to partner with an advisor.
If you have questions about casualty losses, tax relief associated with disaster recovery or helping your business after a hurricane, please contact us to have a tax and disaster recovery financial expert reach out to you.
This article was originally published in October 2018 and was most recently updated with new information and insight on October 30, 2026.
